Finance
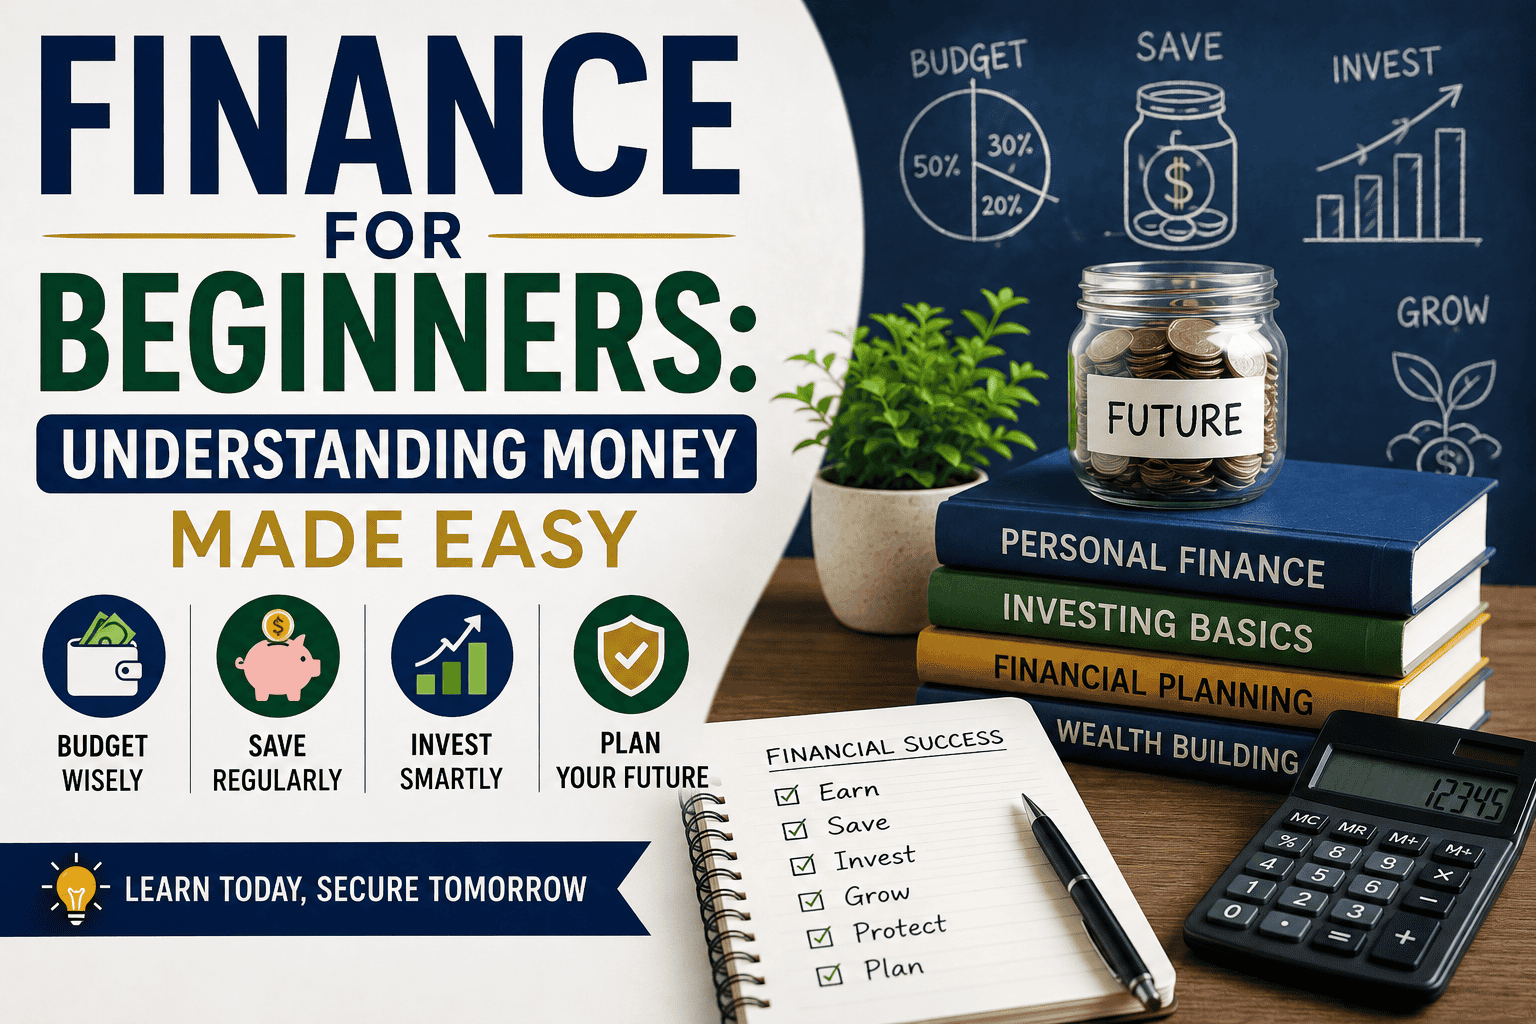
Understand the system that turns money into decisions. Finance explores how individuals, businesses, and institutions manage money — covering how capital is raised, invested, allocated, and grown over time to achieve financial goals. It spans core areas like personal finance, corporate finance, investing, and financial markets, examining how risk, return, and time value shape every financial decision. This field blends quantitative analysis with strategic thinking, revealing how everything from interest rates to market trends influences the flow of capital across the global economy. At its core, finance asks how we make smart decisions about money — today, and for the future.
Content Overview
- 1. Finance: A Comprehensive Guide
- 2. What Is Finance?
- 3. Types of Finance
- 4. Core Financial Concepts
- 5. Financial Statements and Analysis
- 6. Risk Management
- 7. Financial Markets and Institutions
- 8. Corporate Finance Advanced Topics
- 9. Management Accounting and Finance
- 10. Fintech and the Future of Finance
- 11. Conclusion: The Enduring Importance of Finance
1. Finance: A Comprehensive Guide
Finance is the lifeblood of modern civilization. It is the study of money, capital, and financial decision-making — how money is earned, saved, invested, borrowed, spent, and managed over time. Finance is not just about money itself, but about how decisions about money are made under conditions of uncertainty and risk. From an individual’s daily budgeting to multinational corporations making billion-dollar investments, finance provides the tools and frameworks for making sound financial decisions.
This comprehensive guide covers the entire spectrum of finance — from foundational concepts and types of finance to financial markets, instruments, institutions, and advanced topics like behavioral finance, Islamic finance, and fintech. Whether you are a student, professional, or simply someone who wants to understand money better, this guide will provide you with deep, practical knowledge.
2. What Is Finance?
2.1 Definition and Core Concepts
Finance is the study of money, capital, and financial decision-making. It explains how money is earned, saved, invested, borrowed, spent, and managed over time. Finance is not just about money itself, but about how decisions about money are made under uncertainty and risk.
Every financial decision involves three basic questions:
- How much money is needed? — Determining the required amount for a goal, purchase, or investment.
- Where will the money come from? — Identifying sources such as personal savings, borrowing, or equity.
- How should the money be used to get the best result? — Allocating resources to maximize returns, minimize costs, or achieve objectives.
Finance provides the tools, frameworks, and analytical methods to answer these questions rationally. It is both a science (using data, mathematics, and economics) and an art (involving judgment, strategy, and psychology).
At its core, finance involves making informed decisions when the future and its outcomes are uncertain. Unlike accounting, which records what has already happened, finance looks forward — it evaluates future cash flows, assesses risks, and makes choices that balance risk and return.
Finance is essential for:
- Individuals: Managing income, expenses, savings, and investments.
- Businesses: Allocating capital, funding operations, and maximizing shareholder value.
- Governments: Collecting revenue, managing public spending, and ensuring economic stability.
- Economies: Facilitating investment, growth, and efficient resource allocation.
Example: A recent graduate with a job offer must decide how to allocate their salary — how much to spend on rent, how much to save, whether to invest in a retirement account, and whether to take on debt for a car or home. These are all financial decisions. Similarly, a company deciding whether to build a new factory must analyze costs, projected revenues, and risks before committing millions of dollars.
2.2 Why Finance Exists
Finance exists because resources are limited while human needs and wants are unlimited. This fundamental condition of scarcity forces individuals, businesses, and governments to make choices about how to allocate limited money in the most efficient and effective way.
Scarcity creates the need for finance:
- Limited Money: Individuals have limited income; businesses have limited capital; governments have limited tax revenue.
- Unlimited Wants: People want more goods, services, and security; businesses want growth and profits; governments want to meet public needs.
- The Allocation Problem: With limited resources and unlimited wants, decisions must be made about what to fund and what to forego.
Finance helps answer allocation questions:
- Individuals: Should I spend this money on a vacation or save it for emergencies?
- Businesses: Should we invest in marketing, R&D, or new equipment?
- Governments: Should we spend on education, healthcare, or infrastructure?
Finance provides the logic and analytical tools to make these choices rationally — not emotionally or impulsively.
Without finance, resources would be allocated arbitrarily. Finance ensures that money flows to its most productive uses — to individuals who save and invest, to businesses that create value, and to governments that provide public goods.
Example: A student with limited pocket money must decide between buying a new phone or saving for a course that will improve their career prospects. Finance helps them evaluate the long-term value of each option. A company with limited capital must choose between two projects — finance provides tools like Net Present Value (NPV) and Internal Rate of Return (IRR) to select the most profitable one.
2.3 Finance vs Accounting vs Economics
Finance, accounting, and economics are closely related but distinct disciplines. Understanding their differences is essential for grasping the unique role of finance in the broader landscape of business and society.
Accounting — The Past Focus:
Accounting records, classifies, and reports financial transactions that have already occurred. It is historical and rule-based.
- Questions It Answers:
- How much profit was earned last year?
- What is the business’s current cash balance?
- What are the company’s assets and liabilities?
- Characteristics:
- Historical (records the past).
- Rule-based (follows GAAP or IFRS).
- Objective (based on verifiable transactions).
- Compliance-oriented (prepares financial statements).
Finance — The Future Focus:
Finance uses accounting information to make decisions about the future. It is forward-looking, analytical, and decision-oriented.
- Questions It Answers:
- Should the company invest in this project?
- Is borrowing money a good decision?
- Which investment offers the highest return relative to risk?
- Characteristics:
- Forward-looking (focuses on the future).
- Analytical (uses financial models and valuation).
- Decision-oriented (guides choices and strategies).
- Risk-focused (evaluates uncertainty).
Economics — The System Focus:
Economics studies how societies allocate scarce resources at a macro level. It explains the behavior of markets, consumers, and governments.
- Questions It Answers:
- Why do prices rise?
- What causes inflation or unemployment?
- How do markets behave?
- Characteristics:
- Macro-level (focuses on systems and aggregates).
- Theoretical (develops models and theories).
- Broad (covers production, distribution, and consumption).
Simple Relationship:
| Discipline | Focus | Time Orientation |
|---|---|---|
| Accounting | Records facts | Past |
| Finance | Uses facts to decide | Future |
| Economics | Explains the environment | Present & Future |
Finance sits between accounting and economics — it uses the facts from accounting and the theories from economics to make forward-looking financial decisions.
Understanding these distinctions helps individuals and professionals use the right tools for the right purpose. A business manager needs accounting for compliance, finance for decision-making, and economics for understanding the market environment.
Example: An accountant prepares the company’s income statement showing last year’s profit of $5 million. A financial analyst uses that profit data, along with market forecasts, to decide whether the company should invest $10 million in a new product line. An economist analyzes whether the broader economy — interest rates, inflation, consumer spending — will support that investment.
3. Types of Finance
3.1 Personal Finance
Personal finance deals with managing an individual’s money throughout life. It involves all financial decisions made by an individual or household, from daily spending to long-term retirement planning.
Personal finance encompasses:
- Income Planning: Managing earnings from employment, business, investments, or other sources.
- Budgeting: Creating a plan for income and expenses to ensure that spending does not exceed earnings.
- Saving: Setting aside money for future needs, emergencies, and goals.
- Investing: Putting money into assets (stocks, bonds, real estate) to grow wealth over time.
- Insurance: Protecting against financial losses from accidents, illness, or death.
- Retirement Planning: Ensuring sufficient income during retirement through savings, pensions, and investments.
- Debt Management: Borrowing responsibly and repaying loans on time.
- Tax Planning: Minimizing tax liability through legal strategies.
- Estate Planning: Managing the transfer of wealth to heirs.
Key Principles of Personal Finance:
- Spend Less Than You Earn: The foundation of financial health.
- Build an Emergency Fund: 3-6 months of expenses for unexpected events.
- Invest Early and Consistently: Compound interest grows wealth over time.
- Avoid High-Interest Debt: Credit card debt can be financially devastating.
- Plan for the Long Term: Retirement, education, and major purchases require advance planning.
Personal finance is a life skill essential for financial stability, independence, and peace of mind. Without it, individuals are more likely to struggle with debt, stress, and financial insecurity.
Example: A young professional creates a monthly budget: $3,000 income, $1,200 rent, $400 food, $300 transportation, $200 utilities, $500 savings/investments, and $400 discretionary. They build an emergency fund of $9,000 (3 months of expenses), invest $200 monthly in a diversified index fund, and avoid credit card debt. This person is on a path to financial stability and eventual wealth.
3.2 Corporate Finance
Corporate finance focuses on how companies plan, allocate, and manage their financial resources to achieve their business objectives. The ultimate goal is maximizing firm value and shareholder wealth.
Corporate finance revolves around three main decisions:
1. Investment Decisions (Capital Budgeting):
- Which projects should the company invest in?
- How much capital should be allocated to each project?
- Methods: Net Present Value (NPV), Internal Rate of Return (IRR), Payback Period.
2. Financing Decisions (Capital Structure):
- Where should funds come from — debt (borrowing) or equity (issuing shares)?
- What is the optimal mix of debt and equity to minimize cost of capital?
- Factors: Cost of debt vs. cost of equity, risk, tax implications.
3. Dividend Decisions:
- Should profits be reinvested in the business or distributed to shareholders?
- What proportion of earnings should be paid as dividends?
- Factors: Growth opportunities, shareholder preferences, tax considerations.
Other Corporate Finance Activities:
- Working Capital Management: Managing short-term assets and liabilities (cash, inventory, receivables, payables).
- Mergers and Acquisitions: Evaluating and financing acquisitions.
- Risk Management: Hedging against financial risks (currency, interest rate, commodity).
- Financial Planning: Forecasting and budgeting.
Corporate finance is the backbone of business strategy. It ensures that funds are used efficiently, investments are profitable, and the company remains financially healthy and competitive.
Example: A manufacturing company is considering investing $50 million in a new factory. The finance team calculates the NPV and IRR of the project — if the NPV is positive (the present value of future cash flows exceeds the investment), the project is approved. They must then decide whether to finance the project through bank loans (debt) or issuing new shares (equity), weighing the cost of each option.
3.3 Public Finance
Public finance focuses on how governments collect revenue and use it for public spending. It deals with the financial activities of government at all levels — federal, state, and local.
Public finance includes:
- Taxation: How governments collect revenue through income tax, sales tax, corporate tax, property tax, and other levies.
- Public Expenditure: How governments spend money on public goods and services — healthcare, education, defense, infrastructure, social welfare.
- Budgeting: The process of planning and allocating government revenue and expenditure.
- Public Debt: Borrowing by governments through bonds and other instruments.
- Fiscal Policy: Using taxation and spending to influence the economy.
- Subsidies and Grants: Financial support to specific sectors or groups.
- Welfare Programs: Government support such as social security, unemployment assistance, and food aid for people in need.
Key Principles of Public Finance:
- Economic Efficiency: Resources should be allocated where they provide the greatest public benefit.
- Equity: The tax system and spending should be fair and just.
- Stability: Government finance should support economic stability and growth.
- Transparency: Public finances should be open and accountable.
Public finance is essential for economic stability, public welfare, and the provision of services that the private sector cannot provide efficiently. It funds the infrastructure and institutions that society depends on.
Example: A government receives $1 trillion in tax revenue. It allocates $300 billion to defense, $200 billion to healthcare, $150 billion to education, $100 billion to infrastructure, $100 billion to social security, and $50 billion to debt servicing. This budget reflects the government’s priorities and economic strategy.
3.4 Investment Finance
Investment finance focuses on earning returns by investing money in financial assets. It involves the analysis, selection, and management of investments to achieve specific financial goals.
Investment finance covers:
- Asset Classes:
- Stocks: Ownership shares in companies.
- Bonds: Debt instruments issued by governments or corporations.
- Mutual Funds: Pooled investments managed by professionals.
- Exchange-Traded Funds (ETFs): Traded like stocks but diversified like mutual funds.
- Real Estate: Property investments for rental income or capital appreciation.
- Commodities: Gold, oil, agricultural products.
- Derivatives: Options, futures, and other financial contracts.
- Investment Analysis:
- Fundamental Analysis: Assessing an asset’s true value by examining its financial condition, management quality, and position in the market.
- Technical Analysis: Examining historical price movements and market trends to identify patterns and potential future movements.
- Quantitative Analysis: Applying mathematical models and statistical methods to evaluate data and identify potential investment opportunities.
- Risk vs. Return:
- Higher potential returns are typically associated with greater levels of risk.
- Risk can be managed through diversification and asset allocation.
- Portfolio Management: Building and managing a diversified portfolio to meet investment objectives.
- Performance Measurement: Evaluating returns and risk-adjusted performance.
Investment finance helps individuals and institutions grow their wealth. It channels capital to productive uses, supporting economic growth and innovation.
Example: An investor with $100,000 to invest decides to allocate 60% to stocks (for growth), 30% to bonds (for income and stability), and 10% to real estate (for diversification). Within stocks, they diversify across different sectors — technology, healthcare, financials — to spread risk. This balanced portfolio aims to achieve long-term growth with manageable risk.
3.5 International Finance
International finance deals with cross-border financial activities. It focuses on how money flows between countries, how exchange rates are determined, and how multinational corporations manage financial risks in a global environment.
International finance includes:
- Foreign Exchange (Forex) Markets: Where currencies are traded. Exchange rates determine the value of one currency relative to another.
- Exchange Rate Risk: The risk that currency fluctuations will affect international transactions and investments.
- International Trade Financing: Payment mechanisms for global trade — letters of credit, export financing.
- Multinational Financial Management: Managing the finances of companies operating in multiple countries.
- Cross-Border Investments: Foreign direct investment (FDI) and international portfolio investment.
- Global Capital Markets: International bonds, Eurobonds, and sovereign debt.
- Balance of Payments: A record of a country’s transactions with the rest of the world.
- International Financial Institutions: IMF, World Bank, and other organizations that support global financial stability.
Key Risks in International Finance:
- Currency Risk: Fluctuations in exchange rates.
- Political Risk: Changes in government, policy, or stability.
- Country Risk: Economic and political conditions in a foreign country.
- Interest Rate Risk: Differences in interest rates across countries.
International finance is essential in our globalized world. It enables trade, investment, and economic cooperation between nations. Understanding it is critical for businesses and governments operating internationally.
Example: A US-based company sells products in Europe. The company invoices in euros. If the euro weakens against the dollar, the company’s revenue in dollars decreases. To manage this currency risk, the company may use hedging strategies — entering into forward contracts to lock in exchange rates.
3.6 Behavioral Finance
Behavioral finance examines how human psychology influences financial choices and market behavior. It challenges the traditional assumption that people are always rational in their financial decisions.
Traditional finance assumes that markets are efficient and that people make rational decisions based on available information. Behavioral finance shows that this is not always true:
- Emotions: Fear, greed, and overconfidence affect decision-making.
- Cognitive Biases: Systematic errors in thinking that lead to poor decisions.
- Psychological Factors: People are influenced by emotions and mental shortcuts.
Common Behavioral Biases:
- Overconfidence Bias: Believing that one’s knowledge or skill is greater than it actually is. Leads to excessive trading and risk-taking.
- Loss Aversion: The pain of losing money is psychologically stronger than the pleasure of gaining the same amount. People hold onto losing investments to avoid realizing the loss.
- Herd Behavior: Following the crowd — buying when everyone is buying, selling when everyone is selling. Creates market bubbles and crashes.
- Confirmation Bias: Seeking out information that confirms pre-existing beliefs and ignoring contradictory evidence.
- Anchoring: Giving too much importance to the first information received and allowing it to influence later decisions.
- Mental Accounting: Treating money differently depending on its source or intended use.
Impact on Markets:
- Market Bubbles: Prices can become detached from fundamentals due to excessive optimism and herd behavior.
- Panic Selling: Fear can cause markets to crash.
- Momentum: Prices can trend in one direction as investors follow the herd.
Understanding behavioral finance helps investors and financial professionals make better decisions. Awareness of biases can improve investment strategies, reduce errors, and lead to more rational financial behavior.
Example: During a stock market boom, many investors buy stocks because everyone else is buying (herd behavior). They ignore warnings that stocks are overvalued. When the market eventually crashes, they panic and sell at a loss (panic selling). A behavioral finance perspective would recommend staying disciplined, sticking to a long-term investment plan, and not following the crowd.
3.7 Islamic Finance
Islamic finance is a financial system that operates in accordance with Sharia law — the moral and religious code of Islam. It is based on ethical principles that prohibit certain types of transactions.
Key Principles of Islamic Finance:
- Prohibition of Riba (Interest): Charging or paying interest is strictly forbidden. Money itself has no intrinsic value — it is simply a medium of exchange and cannot generate profit on its own.
- Prohibition of Gharar (Excessive Uncertainty): Contracts involving excessive uncertainty, ambiguity, or speculation are prohibited.
- Prohibition of Maysir (Gambling): Speculative transactions that resemble gambling are forbidden.
- Risk Sharing: Financial transactions should involve sharing risks and rewards between parties. Profit is earned through partnership, not interest.
- Asset-Backed Transactions: Finance must be linked to real, tangible assets. Investments must support productive activities.
- Ethical Investments: Investments in businesses that are harmful (alcohol, gambling, pork products, weapons) are prohibited.
Key Islamic Finance Instruments:
- Mudarabah: A profit-sharing partnership. One party provides capital, the other provides expertise. Profits are shared as agreed; losses are borne by the capital provider.
- Musharakah: A joint partnership where all parties contribute capital and expertise. Profits and losses are shared proportionally.
- Ijarah: A leasing arrangement. The financier buys an asset and leases it to the client for a fixed period.
- Sukuk: Islamic bonds. Instead of paying interest, sukuk represent ownership in an asset or project. Investors earn a share of the profits.
- Takaful: An Islamic form of insurance based on mutual support, where participants contribute to a shared fund used to cover eligible claims and losses.
Islamic finance is a rapidly growing sector, serving Muslim communities worldwide. It is also attracting non-Muslims who are drawn to its ethical and risk-sharing principles.
Example: A Muslim entrepreneur needs $1 million to start a business. Instead of taking a conventional bank loan with interest (riba), they enter a Mudarabah partnership with an Islamic bank. The bank provides the capital, and the entrepreneur provides the expertise. Profits are shared according to a pre-agreed ratio, and losses are borne by the bank.
3.8 Green and Sustainable Finance
Green and sustainable finance focuses on investments that benefit the environment and promote sustainable development. It links financial decisions with environmental and social responsibility.
Sustainable finance includes:
- Green Finance: Investments that support environmental goals — renewable energy, clean technology, pollution reduction, sustainable agriculture.
- Social Finance: Investments that support social goals — affordable housing, education, healthcare, community development.
- Environmental, Social, and Governance (ESG) Criteria: A framework for evaluating investments based on environmental impact, social responsibility, and corporate governance.
- Green Bonds: Bonds issued to raise capital for environmental projects.
- Impact Investing: Investing with the intention of generating measurable social or environmental impact alongside financial returns.
- Climate Finance: Funding to address climate change — mitigation (reducing emissions) and adaptation (building resilience).
Why It Matters:
- Climate Change: The financial sector has a role in funding solutions and avoiding investments that worsen the problem.
- Investor Demand: Many investors want their money to align with their values.
- Regulatory Pressure: Governments are increasingly requiring companies to report on ESG factors.
- Risk Management: ESG issues can affect financial performance — regulatory changes, reputation, and physical risks.
Green and sustainable finance is not just about doing good — it is about ensuring the long-term viability of the financial system and the planet. It connects finance with environmental responsibility and sustainable development.
Example: An investment fund raises $500 million through green bonds to finance a portfolio of solar and wind energy projects. The bonds attract investors who want to support renewable energy while earning a competitive return. The projects reduce carbon emissions and create jobs.
4. Core Financial Concepts
4.1 Financial Economics
Financial economics is the branch of economics that applies economic theory to financial markets and financial decision-making. It provides the theoretical foundations for understanding how financial markets work and how financial decisions are made.
Financial economics covers several core concepts:
Time Value of Money:
Money available today is worth more than the same amount in the future because it can be invested and earn a return. This is the foundation of all financial valuation.
- Present Value (PV): The current value of a future cash flow, discounted at an appropriate rate.
- Future Value (FV): The value of an investment at a future date, given a certain rate of return.
- Discounting: The process of converting future cash flows into present value.
- Compound Interest: Earning interest on both the original principal and accumulated interest.
Asset Pricing:
The determination of the price of financial assets — stocks, bonds, derivatives, and other instruments.
- Capital Asset Pricing Model (CAPM): A model that relates the expected return of an asset to its risk (beta). It explains how assets are priced in equilibrium.
- Arbitrage Pricing Theory (APT): A multi-factor model for pricing assets.
- Efficient Market Hypothesis (EMH): The theory that markets are efficient and reflect all available information. Prices cannot be consistently predicted.
Portfolio Theory:
The study of how to construct and manage a portfolio of investments to maximize returns for a given level of risk.
- Risk and Return: Higher returns generally require higher risk.
- Diversification: Spreading investments across different assets reduces portfolio risk without sacrificing returns.
- Efficient Frontier: The set of portfolios that offer the highest expected return for a given level of risk.
- Modern Portfolio Theory (MPT): Harry Markowitz’s theory that rational investors should hold diversified portfolios on the efficient frontier.
Market Efficiency:
The extent to which current market prices incorporate all relevant and available information.
- Weak Form Efficiency: Prices reflect past price data. Technical analysis is useless.
- Semi-Strong Form Efficiency: Prices reflect all public information. Fundamental analysis is useless.
- Strong Form Efficiency: Market prices incorporate all available information, including both public and private information, making it impossible to consistently achieve higher-than-normal returns, even with insider knowledge.
Financial economics provides the theoretical framework for practical financial decisions. It explains why prices are what they are, why markets behave the way they do, and how investors can make rational choices.
Example: An investor is offered a choice between receiving $10,000 today or $10,000 in one year. Using the time value of money, they calculate the present value of $10,000 received one year from now at a 5% discount rate: $10,000 / 1.05 = $9,524. Therefore, receiving $10,000 today is worth more. If the investor can earn 5% by investing the $10,000 today, they would have $10,500 in one year.
4.2 Time Value of Money
The Time Value of Money (TVM) is the principle that a dollar today is worth more than a dollar in the future because money can be invested to earn a return. It is the single most important concept in finance.
- Present Value (PV): The value today of a future sum of money or stream of cash flows, discounted at a specific rate.
- Formula: PV = FV / (1 + r)^n
- Future Value (FV): The value of an investment at a future date, given a specific rate of return.
- Formula: FV = PV × (1 + r)^n
- Discount Rate (r): The rate used to discount future cash flows to present value. It reflects the opportunity cost of capital, inflation, and risk.
- Number of Periods (n): The number of compounding periods (years, months, quarters).
- Compounding: Earning interest on both the original principal and the accumulated interest.
- Annuities: A series of equal payments made at regular intervals.
- Ordinary Annuity: Payments at the end of each period.
- Annuity Due: Payments at the beginning of each period.
- Perpetuity: An infinite series of equal payments.
Time value of money is the foundation of all financial valuation — it underlies stock valuation, bond pricing, capital budgeting, and retirement planning. Without it, financial decisions cannot be made rationally.
Example: If you invest $1,000 today at an annual interest rate of 5% compounded annually, the future value after 10 years is: FV = $1,000 × (1.05)^10 = $1,628.89. Conversely, if you will receive $1,000 in 10 years, and the discount rate is 5%, the present value is: PV = $1,000 / (1.05)^10 = $613.91. This means that receiving $1,000 in 10 years is equivalent to receiving $613.91 today.
4.3 Asset Pricing
Asset pricing is the determination of the fair value or price of financial assets — stocks, bonds, derivatives, real estate, and other investments. It involves estimating the present value of expected future cash flows.
Key Asset Pricing Models:
- Discounted Cash Flow (DCF): The value of an asset is the present value of its expected future cash flows, discounted at an appropriate rate.
- For stocks: Value = Present value of future dividends.
- For bonds: Value = Present value of future coupon payments and principal.
- Capital Asset Pricing Model (CAPM): The expected return on an asset is the risk-free rate plus a risk premium based on the asset’s beta (systematic risk).
- Formula: E(Ri) = Rf + βi × (E(Rm) – Rf)
- Arbitrage Pricing Theory (APT): A multi-factor model — asset returns are driven by multiple factors (inflation, GDP growth, interest rates, etc.).
- Dividend Discount Model (DDM): A stock’s value is the present value of expected future dividends.
- Bond Pricing: A bond’s price is the present value of its future coupon payments and principal repayment.
Asset pricing models help investors determine whether an asset is undervalued or overvalued, enabling informed investment decisions.
Example: A stock pays an annual dividend of $2 per share, and dividends are expected to grow at 3% per year. The required rate of return is 10%. Using the Gordon Growth Model (a DDM variant), the stock’s value is: P = D1 / (r – g) = $2.06 / (0.10 – 0.03) = $29.43. If the stock is currently trading at $25, it is undervalued and a good buy.
4.4 Portfolio Theory and Diversification
Portfolio theory is the study of how to construct and manage a portfolio of investments to maximize returns for a given level of risk. Diversification is the practice of spreading investments across different assets to reduce risk.
Modern Portfolio Theory (MPT):
Developed by Harry Markowitz (Nobel Prize winner), MPT shows that investors can reduce portfolio risk by combining assets that are not perfectly correlated.
- Risk: The variability of returns (measured by standard deviation).
- Systematic Risk: Market-wide risk (inflation, interest rates, political instability). Cannot be diversified away.
- Unsystematic Risk: Company-specific risk (management, product recall). Can be diversified away.
- Return: The expected gain from an investment.
- Correlation: A measure of how closely the returns of two or more assets move in relation to each other.
- Perfect Positive Correlation (+1): They move in the same direction.
- Perfect Negative Correlation (-1): They move in opposite directions.
- Zero Correlation (0): No relationship.
- Diversification: Combining assets with low or negative correlation reduces overall portfolio risk. The unsystematic risk is eliminated, and only systematic risk remains.
- Efficient Frontier: The set of optimal portfolios that offer the highest expected return for a given level of risk. Rational investors will hold portfolios on the efficient frontier.
- Capital Market Line (CML): Shows the relationship between risk and return for efficient portfolios.
Portfolio theory and diversification are essential for building investment portfolios that balance risk and return. They help investors avoid putting all their eggs in one basket.
Example: An investor holds a portfolio consisting of 50% stocks and 50% bonds. During a recession, stocks may decline, but bonds may rise (as interest rates fall). The diversification reduces the portfolio’s overall volatility. If the investor instead held 100% stocks, a market crash would cause a significant loss. By diversifying, the investor achieves a smoother return profile over time.
4.5 Market Efficiency
Market efficiency is the degree to which market prices reflect all available information. The Efficient Market Hypothesis (EMH) states that asset prices fully reflect all available information, making it impossible to consistently outperform the market through analysis.
Three Forms of Market Efficiency:
- Weak Form Efficiency: Prices reflect all past price data (historical prices and trading volume). Technical analysis (studying price patterns) cannot generate consistently superior returns.
- Semi-Strong Form Efficiency: Prices reflect all publicly available information (financial statements, news, economic data). Fundamental analysis (analyzing financial health) cannot generate consistently superior returns.
- Strong Form Efficiency: Prices reflect all information, public and private (including insider information). Even insider trading cannot generate consistently superior returns.
Implications:
- If markets are efficient: Active management (stock picking, market timing) is futile. Investors should use passive strategies (index funds, ETFs).
- If markets are not efficient: There are opportunities for active management to generate superior returns.
Arguments For and Against Efficiency:
- For: Markets are highly liquid, information is widely disseminated, and competition among investors quickly incorporates information into prices.
- Against: Behavioral biases (herd behavior, overconfidence) create market anomalies. There are recurring patterns (momentum, value effect) that seem inconsistent with efficiency.
Market efficiency has profound implications for investment strategy. It determines whether active management can add value or whether passive investing is the superior approach.
Example: A fund manager believes they can beat the market by analyzing companies’ financial statements and identifying undervalued stocks. If the market is semi-strong efficient, this approach is unlikely to succeed because public information is already reflected in stock prices. The manager would be better off investing in a low-cost index fund that tracks the entire market.
5. Financial Statements and Analysis
5.1 Financial Statements
Financial statements are formal records of a company’s financial activities and position. They provide essential information for decision-making by investors, creditors, analysts, and management.
The Income Statement (Performance):
Also known as the Profit and Loss (P&L) statement, it shows the company’s financial performance over a specific period (quarter or year).
- Revenue: Money earned from sales.
- Cost of Goods Sold (COGS): The direct expenses involved in producing the goods that a business sells.
- Gross Profit: Revenue – COGS.
- Operating Expenses: The ongoing costs of running a business, including selling and administrative expenses, research and development, and depreciation.
- Operating Income: Gross Profit – Operating Expenses.
- Interest and Taxes: Interest expense and income tax.
- Net Income: The final profit remaining after a business has deducted all expenses, including taxes and other costs.
The Balance Sheet (Financial Position):
Shows the company’s financial position at a specific point in time (as of a date).
- Assets: What the company owns — current (cash, inventory, receivables) and non-current (property, equipment, intangibles).
- Liabilities: What the company owes — current (payables, short-term debt) and non-current (long-term debt, deferred taxes).
- Equity: The owners’ claim — common stock, retained earnings.
- Accounting Equation: Assets = Liabilities + Equity.
The Cash Flow Statement (Liquidity):
Shows the company’s cash inflows and outflows over a period.
- Operating Cash Flow: The amount of cash generated or used through a company’s regular business activities.
- Investing Cash Flow: Cash from buying/selling assets.
- Financing Cash Flow: Cash from borrowing, repaying debt, issuing stock, paying dividends.
- Net Change in Cash: The difference between beginning and ending cash.
The Statement of Changes in Equity:
Shows changes in owners’ equity during the period — share issuance, dividends, net income.
Financial statements provide essential information used to evaluate a company’s financial performance and support informed financial decisions. They help investors assess profitability, creditors evaluate creditworthiness, and management monitor performance.
Example: An investor analyzes a company’s financial statements and finds $100 million in revenue, $60 million in COGS, $20 million in operating expenses, and $15 million in net income. The balance sheet reports $200 million in assets, $120 million in liabilities, and $80 million in equity. The company also generates $20 million in positive operating cash flow. Together, these figures suggest that the company is profitable, financially stable, and generating healthy cash from its core operations.
5.2 Financial Ratios
Financial ratios are quantitative measures used to evaluate a company’s financial performance, health, and valuation. They are calculated from financial statements and provide insights into different aspects of the business.
Liquidity Ratios:
Measures a company’s ability to pay its short-term financial obligations when they become due.
- Current Ratio: Current Assets / Current Liabilities. Higher is better.
- Quick Ratio: (Current Assets – Inventory) / Current Liabilities. More conservative measure.
Solvency Ratios:
Measures a company’s ability to meet its long-term financial obligations and remain financially stable over time.
- Debt-to-Equity Ratio: Total Debt / Total Equity. Measures financial leverage.
- Interest Coverage Ratio: EBIT / Interest Expense. Measures ability to pay interest.
Profitability Ratios:
Measure how efficiently the company generates profit.
- Gross Profit Margin: Gross Profit / Revenue.
- Operating Profit Margin: Operating Income / Revenue.
- Net Profit Margin: Net Income / Revenue.
- Return on Assets (ROA): Net Income / Total Assets.
- Return on Equity (ROE): Net Income / Total Equity.
Efficiency Ratios:
Measure how effectively the company uses its assets.
- Inventory Turnover: COGS / Average Inventory.
- Receivables Turnover: Revenue / Average Accounts Receivable.
- Asset Turnover: Revenue / Total Assets.
Valuation Ratios:
Measure the company’s market value relative to its financial performance.
- Price-to-Earnings (P/E) Ratio: A valuation measure calculated by dividing a company’s share price by its earnings per share (EPS).
- Price-to-Book (P/B) Ratio: A valuation measure calculated by dividing a company’s share price by its book value per share.
- Dividend Yield: Annual Dividend / Price per Share.
Financial ratios enable meaningful comparisons — across time, across companies, and across industries. They are essential tools for investment analysis, credit analysis, and management monitoring.
Example: A company has current assets of $10 million and current liabilities of $5 million, giving a current ratio of 2.0 (good). Total debt is $8 million, and equity is $12 million, giving a debt-to-equity ratio of 0.67 (moderate leverage). Net income is $2 million on revenue of $20 million, giving a net profit margin of 10%. The company is liquid, moderately leveraged, and profitable.
5.3 Financial Planning and Forecasting
Financial planning is the process of setting financial goals and developing strategies to achieve them. Forecasting involves projecting future financial performance based on historical data and assumptions.
Financial Planning:
- Strategic Planning: Long-term goals (5-10 years) — market expansion, product development, acquisitions.
- Operational Planning: Short-term goals (1 year) — budgeting, resource allocation, performance targets.
- Capital Budgeting: Planning for major investments — new facilities, equipment, acquisitions.
- Financial Forecasting: Projecting revenue, expenses, profits, and cash flows.
- Scenario Analysis: Evaluating different possible outcomes based on varying assumptions.
- Sensitivity Analysis: Assessing the impact of changes in key variables.
Forecasting Methods:
- Qualitative Methods: Expert judgment, market research, Delphi technique.
- Quantitative Methods: Time series analysis, regression analysis, econometric models.
- Top-Down Forecasting: Start with macroeconomic forecasts, then industry, then company.
- Bottom-Up Forecasting: Start with individual business units and aggregate.
Financial planning and forecasting provide direction and accountability. They help companies allocate resources efficiently, anticipate challenges, and measure performance against goals.
Example: A company’s finance team forecasts next year’s revenue at $50 million based on market growth of 5%, new product launches, and increased marketing spend. They project expenses of $40 million, resulting in net income of $10 million. The forecast is used to set performance targets, allocate budgets, and secure financing if needed.
6. Risk Management
6.1 Understanding Risk
Risk is the uncertainty about future outcomes. It is the possibility that actual results will differ from expected results, potentially causing financial loss. Finance is fundamentally about managing risk.
Types of Risk:
- Market Risk: The risk of losses due to market movements — stock prices, interest rates, exchange rates, commodity prices.
- Credit Risk: The risk of default — the borrower fails to repay a loan or meet contractual obligations.
- Liquidity Risk: The risk that an asset cannot be sold quickly without significant loss.
- Operational Risk: The risk of losses due to failures in internal processes, systems, or human error — fraud, system failures, supply chain disruptions.
- Systemic Risk: The risk that the failure of one institution or event triggers a collapse of the entire financial system.
- Inflation Risk: The risk that inflation erodes purchasing power.
- Legal and Regulatory Risk: The risk of losses due to changes in laws or regulations.
- Reputation Risk: The risk of loss of reputation affecting business and financial performance.
Risk cannot be eliminated, but it can be managed — through identification, assessment, mitigation, and monitoring. Effective risk management is essential for financial stability and performance.
Example: A company selling products internationally faces exchange rate risk — if the US dollar strengthens against the euro, the company’s revenue in dollars decreases. The company can mitigate this risk through hedging (using forward contracts or options).
6.2 Risk Management Strategies
Risk management is the process of identifying, assessing, and mitigating risks to reduce their potential impact on an organization or individual.
Risk Management Process:
- Risk Identification: Identify all potential risks that could affect financial performance.
- Risk Assessment: Evaluate the likelihood and potential impact of each risk.
- Risk Mitigation: Develop strategies to reduce or manage risks.
- Risk Monitoring: Continuously monitor risks and adjust strategies as needed.
Risk Mitigation Strategies:
- Risk Avoidance: Eliminating the activity that creates the risk.
- Risk Reduction: Implementing measures to reduce the likelihood or impact of risk (e.g., safety protocols, diversification, internal controls).
- Risk Transfer: Shifting risk to another party (e.g., insurance, hedging with derivatives).
- Risk Acceptance: Acknowledging the risk and accepting potential losses (e.g., self-insurance, retention).
Financial Risk Management Tools:
- Diversification: Spreading investments across different assets, sectors, and geographies to reduce unsystematic risk.
- Hedging: Using financial instruments (options, futures, forwards, swaps) to offset potential losses from market movements.
- Insurance: Transferring risk to an insurance company.
- Derivatives: Contracts whose value is derived from an underlying asset — used for hedging and speculation.
- Stress Testing: Simulating extreme scenarios to assess vulnerability.
Effective risk management protects financial assets, ensures stability, and supports long-term growth. Without it, organizations and individuals are vulnerable to financial ruin.
Example: A company with significant foreign currency exposure enters into a forward contract to lock in the exchange rate for future sales. If the exchange rate moves against them, the forward contract offsets the loss. This hedging strategy reduces the company’s currency risk.
6.3 Derivatives and Hedging
Derivatives are financial contracts whose value is derived from an underlying asset — stocks, bonds, commodities, currencies, interest rates, or market indices. They are primarily used for hedging (risk management) and speculation.
Types of Derivatives:
- Forward Contracts: An agreement to buy or sell an asset at a specified price on a future date. Private, customized contracts.
- Futures Contracts: Similar to forwards but standardized, traded on exchanges, and marked-to-market daily.
- Options: Contracts that give the buyer the right (but not the obligation) to buy (call option) or sell (put option) an asset at a specified price on or before a specific date.
- Swaps: Agreements to exchange cash flows or liabilities. Common: interest rate swaps, currency swaps.
Hedging:
Hedging involves using derivatives to offset potential losses from adverse market movements.
- Protective Put: Buying a put option to protect against a decline in stock price.
- Interest Rate Swap: Exchanging fixed-rate debt for floating-rate debt to manage interest rate exposure.
- Currency Forward: Locking in exchange rates for foreign currency receivables.
Speculation:
Derivatives can also be used for speculation — betting on the direction of market movements. This can yield high returns but also involves high risk.
Derivatives are essential for risk management. They allow companies, investors, and financial institutions to transfer and manage risks efficiently.
Example: An airline expects to purchase jet fuel in six months and is concerned about rising oil prices. It enters into a futures contract to buy oil at the current price. If oil prices rise, the futures contract locks in the lower price, saving the airline money. This hedging strategy protects against price volatility.
7. Financial Markets and Institutions
7.1 Financial Markets
Financial markets are platforms or systems where buyers and sellers trade financial assets — stocks, bonds, commodities, currencies, and derivatives. They facilitate the flow of capital from savers to borrowers.
Types of Financial Markets:
- Capital Markets: For long-term (more than one year) securities.
- Stock Market: Where shares of publicly traded companies are bought and sold. Examples: NYSE, NASDAQ.
- Bond Market: Where debt securities (bonds) are issued and traded.
- Money Markets: For short-term (one year or less) securities with high liquidity and low risk. Examples: Treasury bills, commercial paper, certificates of deposit.
- Foreign Exchange (Forex) Market: Where currencies are traded. The largest financial market in the world.
- Derivatives Market: Where derivatives (options, futures, swaps) are traded. Can be exchange-traded or over-the-counter (OTC).
- Commodity Markets: Where physical commodities (gold, oil, wheat) are traded.
Functions of Financial Markets:
- Price Discovery: Determining the price of assets through supply and demand.
- Liquidity: Providing a platform for buying and selling assets.
- Capital Formation: Channeling savings into productive investments.
- Risk Sharing: Allowing investors to diversify and transfer risk.
- Information Processing: Aggregating and disseminating information.
Financial markets are essential for economic growth. They allocate capital to its most productive uses, provide liquidity, and enable risk management.
Example: A company needs to raise $100 million for a new factory. It can issue shares (equity) on the stock market or sell bonds (debt) on the bond market. Savers, such as retirement funds and individual investors, buy these securities, providing the capital the company needs. The stock market provides liquidity — investors can sell their shares later if needed.
7.2 Financial Institutions
Financial institutions are organizations that provide financial services — accepting deposits, making loans, facilitating investments, and managing risks.
Types of Financial Institutions:
- Banks: Accept deposits and make loans. Provide checking and savings accounts, credit cards, and mortgages.
- Commercial Banks: Retail and corporate banking.
- Investment Banks: Underwriting, advisory, trading, and research.
- Insurance Companies: Provide protection against financial losses (life, health, property, casualty).
- Investment Companies: Manage pooled investments — mutual funds, ETFs, hedge funds.
- Brokerage Firms: Facilitate buying and selling of securities — stockbrokers, online brokers.
- Pension Funds: Manage retirement savings on behalf of employees.
- Credit Unions: Member-owned cooperatives offering banking services.
- Central Banks: National banks that regulate the money supply, interest rates, and financial stability. Examples: Federal Reserve (US), European Central Bank (ECB), State Bank of Pakistan.
Financial institutions play a central role in supporting and maintaining the overall financial system. They channel funds from savers to borrowers, provide essential services, and ensure the smooth functioning of the economy.
Example: A small business owner needs a loan to expand. They approach a commercial bank, which assesses their creditworthiness and provides a loan. The bank’s deposits come from individual savers, who earn interest on their deposits. This intermediation process enables economic activity.
7.3 Central Banking and Monetary Policy
Central banking refers to the role of a country’s central bank in managing the money supply, interest rates, and financial stability. Monetary policy is the use of these tools to achieve economic goals — controlling inflation, promoting employment, and supporting economic growth.
Functions of Central Banks:
- Monetary Policy: Managing the money supply and interest rates.
- Expansionary Policy: Increasing money supply, lowering interest rates to stimulate the economy (during recessions).
- Contractionary Policy: Decreasing money supply, raising interest rates to control inflation (during booms).
- Lender of Last Resort: Providing liquidity to banks in times of crisis.
- Bank Regulation and Supervision: Ensuring the safety and soundness of the banking system.
- Currency Issuance: Issuing and managing the national currency.
- Payment System Oversight: Ensuring efficient and secure payment systems.
Monetary Policy Tools:
- Open Market Operations: Buying or selling government securities to influence the money supply and interest rates.
- Discount Rate: The interest rate at which banks can borrow from the central bank.
- Reserve Requirements: The percentage of deposits that banks must hold as reserves.
- Interest on Reserves: Paying interest on bank reserves to influence lending.
Central banking and monetary policy are essential for macroeconomic stability. They manage inflation, support employment, and prevent financial crises.
Example: The Federal Reserve lowers the federal funds rate during a recession to encourage borrowing and investment. This stimulates economic activity — businesses can borrow cheaply to expand, and consumers can borrow to spend. The lower interest rates also reduce the cost of mortgages and auto loans, boosting consumer demand.
7.4 Financial Crises
Financial crises are severe disruptions in financial markets that lead to a sharp decline in asset prices, liquidity shortages, and widespread financial distress. They often have devastating effects on the real economy.
Types of Financial Crises:
- Banking Crises: Widespread bank failures due to runs or insolvency.
- Currency Crises: Sharp devaluation of a currency due to speculative attacks.
- Debt Crises: Inability to service sovereign or corporate debt.
- Systemic Crises: Collapse of the entire financial system.
- Stock Market Crashes: Rapid, severe decline in stock prices.
Causes of Financial Crises:
- Excessive Leverage: High levels of debt make institutions vulnerable.
- Asset Bubbles: Overvaluation of assets followed by a crash.
- Liquidity Shortages: Inability to meet short-term obligations.
- Regulatory Failures: Inadequate oversight.
- Contagion: Failure spreads from one institution to another.
- Systemic Risk: Interconnectedness of institutions.
Historical Examples:
- Great Depression (1929): Stock market crash → banking crisis → economic depression.
- Asian Financial Crisis (1997): Currency and debt crises in several Asian countries.
- Global Financial Crisis (2008): US housing bubble → subprime mortgage crisis → banking crisis → global recession.
- European Sovereign Debt Crisis (2010): Debt issues in Greece, Ireland, Portugal, Spain, and Italy.
- COVID-19 Crisis (2020): Pandemic-induced economic and financial shock.
Understanding financial crises is essential for preventing them and mitigating their impact. The lessons from past crises lead to better regulation, oversight, and crisis management.
Example: The 2008 Global Financial Crisis was triggered by the collapse of the US housing market. Subprime mortgages (high-risk loans) were packaged into mortgage-backed securities and sold to investors worldwide. When housing prices fell and defaults increased, these securities lost value, causing massive losses at banks and financial institutions. Lehman Brothers collapsed, triggering a global financial panic. The crisis led to major reforms, including the Dodd-Frank Act and increased capital requirements.
8. Corporate Finance Advanced Topics
8.1 Capital Budgeting
Capital budgeting is the process of evaluating and selecting long-term investments that are consistent with the company’s goal of maximizing shareholder value. It involves analyzing potential projects and deciding which ones to pursue.
Capital Budgeting Methods:
- Net Present Value (NPV): The difference between the present value of a project’s future cash flows and its initial investment. A project is generally accepted when NPV > 0.
- Formula: NPV = ∑ [CFt / (1 + r)^t] – Initial Investment
- Internal Rate of Return (IRR): The discount rate at which a project’s NPV becomes zero. A project is generally accepted when the IRR exceeds the cost of capital.
- Payback Period: The time required to recover the initial investment. Shorter payback periods are preferred.
- Profitability Index (PI): Present value of future cash flows divided by the initial investment. PI > 1 is acceptable.
- Discounted Payback: The time required to recover an initial investment based on the present value of future cash flows.
Capital Budgeting Process:
- Generate Ideas: Propose potential projects.
- Estimate Cash Flows: Forecast costs, revenues, and net cash flows.
- Evaluate Projects: Apply NPV, IRR, and other methods.
- Select Projects: Choose the best projects.
- Monitor and Control: Track project performance and make adjustments.
Importance
Capital budgeting ensures that a company invests in projects that create value. Poor investment decisions can destroy shareholder value and jeopardize the company’s future.
Example: A company is considering investing $10 million in a new production line. The project is expected to generate $3 million in cash flows per year for 5 years. The company’s cost of capital is 10%. The NPV is calculated as -$10M + $3M/1.10 + $3M/(1.10)^2 + … + $3M/(1.10)^5. If the NPV is positive (say $1.37 million), the project is accepted. The IRR would be approximately 15%, which is higher than the cost of capital (10%), so the project is also acceptable.
8.2 Cost of Capital
The cost of capital is the rate of return that a company must pay to its investors — debt holders and equity holders — to finance its assets. It is the minimum return required to justify a capital investment.
Components of Cost of Capital:
- Cost of Debt: The interest rate a company pays on its debt, adjusted for taxes (because interest is tax-deductible).
- Formula: Kd = Interest Rate × (1 – Tax Rate)
- Cost of Equity: The return required by equity investors. Calculated using:
- CAPM: Ke = Rf + β × (Rm – Rf)
- Dividend Discount Model: Ke = (D1 / P0) + g
- Weighted Average Cost of Capital (WACC): The weighted average of the cost of debt and cost of equity, weighted by their proportions in the company’s capital structure.
- Formula: WACC = (E/V) × Ke + (D/V) × Kd × (1 – T)
- Where E = Market value of equity, D = Market value of debt, V = E + D, T = Tax rate.
The cost of capital is an important factor used when evaluating and selecting investment projects. A project must earn a return higher than the WACC to be value-creating. It also affects financing decisions — the optimal capital structure minimizes the WACC.
Example: Suppose a company finances its operations with 60% equity and 40% debt. If the cost of equity is 12%, the cost of debt is 6%, and the corporate tax rate is 30%, the weighted average cost of capital (WACC) is calculated as:
WACC = (0.60 × 12%) + (0.40 × 6% × (1 − 0.30)) = 7.2% + 1.68% = 8.88%
Therefore, a project generally needs to earn more than 8.88% to generate value above the company’s cost of financing.
8.3 Capital Structure
Capital structure refers to the mix of debt and equity that a company uses to finance its operations and growth. It is one of the most important decisions in corporate finance.
Debt vs. Equity:
- Debt: Borrowing money (loans, bonds). Interest is tax-deductible, and debt holders do not have ownership rights. However, debt increases financial risk — interest must be paid regardless of profitability.
- Equity: Issuing shares. No interest payments, but shareholders have ownership and voting rights. Dividends are not tax-deductible.
Theories of Capital Structure:
- Modigliani-Miller Theorem (MM): In a perfect market (no taxes, no bankruptcy costs, no information asymmetry), the value of a firm is independent of its capital structure.
- Trade-Off Theory: Firms balance the tax benefits of debt against the costs of financial distress. There is an optimal capital structure.
- Pecking Order Theory: Firms prefer internal financing (retained earnings), then debt, then equity. They use equity only when other options are exhausted.
Optimal Capital Structure:
The mix of debt and equity that minimizes the WACC and maximizes the firm’s value. It balances the tax benefits of debt against the risk of financial distress.
Capital structure affects the company’s cost of capital, risk profile, and valuation. The optimal structure enhances shareholder value.
Example: A company with a capital structure of 100% equity has no interest obligations but may be giving up the tax benefits of debt. A company with 100% debt has high interest obligations and faces significant bankruptcy risk. The optimal structure might be 60% equity and 40% debt, balancing the tax benefits of debt against financial risk.
8.4 Working Capital Management
Working capital management involves managing the company’s short-term assets and liabilities to ensure efficient operations and sufficient liquidity.
Working Capital:
- Current Assets: Cash, accounts receivable, inventory, marketable securities.
- Current Liabilities: Accounts payable, accrued expenses, short-term debt.
- Net Working Capital: Current Assets – Current Liabilities.
Working Capital Management Decisions:
- Cash Management: Ensuring the company has enough cash on hand for daily operations, but not holding too much (which earns no return).
- Cash Conversion Cycle: The time between paying for inventory and collecting cash from sales.
- Inventory Management: Optimizing inventory levels to avoid stockouts (lost sales) and overstocking (storage costs, obsolescence).
- Techniques: Just-in-Time (JIT), Economic Order Quantity (EOQ).
- Accounts Receivable Management: Managing credit sales and collections.
- Credit terms: Setting payment terms.
- Collection policy: Follow-up on overdue accounts.
- Accounts Payable Management: Managing supplier payments.
- Taking advantage of discounts for early payment.
- Extending payment periods when possible.
Effective working capital management improves cash flow, profitability, and financial health. Poor management can lead to cash shortages, even for profitable companies.
Example: A company has $5 million in cash, $10 million in accounts receivable, $15 million in inventory, and $8 million in accounts payable. The current assets are $30 million, and current liabilities are $8 million. Net working capital is $22 million. The company implements an aggressive collection policy to reduce accounts receivable and uses JIT to reduce inventory, freeing up cash.
8.5 Dividend Policy
Dividend policy refers to the company’s decisions regarding the distribution of profits to shareholders in the form of dividends or reinvestment in the business.
Types of Dividend Policies:
- Constant Dividend Policy: Paying a fixed dividend per share regardless of fluctuations in earnings.
- Constant Payout Ratio: Paying a fixed percentage of earnings as dividends.
- Residual Dividend Policy: Paying dividends only after all profitable investment opportunities have been funded.
Dividend Theories:
- Dividend Irrelevance Theory: In a perfect market, dividend policy does not affect firm value. Investors can create their own dividends by selling shares.
- Bird-in-the-Hand Theory: Investors prefer dividends because they are certain, whereas capital gains are uncertain.
- Tax Preference Theory: Investors prefer capital gains (which are taxed at a lower rate) over dividends.
Factors Affecting Dividend Policy:
- Profitability: More profitable companies have more to distribute.
- Growth Opportunities: Companies with many growth opportunities reinvest profits.
- Cash Flow: Cash flow, not just profits, supports dividends.
- Taxes: Dividends are taxed differently than capital gains.
- Shareholder Preferences: Some investors prefer income (dividends); others prefer growth (capital gains).
Importance
Dividend policy signals management’s confidence in the company’s future. Consistent dividends attract income-oriented investors and support the stock price.
Example: A company has net income of $10 million and is considering paying a dividend of $2 million ($0.50 per share). The remaining $8 million is reinvested in the business to fund new projects. The dividend policy reflects the company’s balance between rewarding shareholders and investing in growth.
9. Management Accounting and Finance
9.1 Management Accounting
Management accounting is the process of using financial and non-financial information to support internal decision-making. It is focused on providing information to managers to help them plan, control, and make decisions.
Key Functions:
- Budgeting: Preparing financial plans for revenues, expenses, and capital expenditures.
- Cost Control: Monitoring and managing costs to ensure efficiency.
- Forecasting: Predicting future financial performance.
- Performance Evaluation: Assessing the performance of departments, products, and individuals.
- Decision Support: Providing information for decisions — pricing, make-or-buy, outsourcing, product mix.
Cost Concepts:
- Fixed Costs: Costs that do not change with production volume (e.g., rent, salaries).
- Variable Costs: Costs that change with production volume (e.g., raw materials, labor).
- Direct Costs: Costs directly attributable to a product (e.g., direct materials, direct labor).
- Indirect Costs: Costs not directly attributable (e.g., overhead).
- Marginal Cost: The additional cost incurred when producing one more unit of a product.
- Opportunity Cost: The benefit or value of the best alternative that is given up when making a choice.
Management accounting provides the information that managers need to make informed decisions, control operations, and achieve strategic objectives. It is essential for planning, monitoring, and improving business performance.
Example: A company is considering whether to accept a special order at a lower price. The management accountant calculates the marginal cost of producing the order and determines that the order will contribute to covering fixed costs and generate a profit. The order is accepted because it increases overall profitability.
9.2 Cost-Volume-Profit Analysis
Cost-Volume-Profit (CVP) analysis is a tool that examines the relationship between costs, sales volume, and profit. It helps managers determine the level of sales needed to cover costs and achieve target profits.
Key Concepts:
- Break-Even Point: The level of sales at which total revenue equals total costs. No profit, no loss.
- Formula (Units): The break-even point in units is calculated by dividing fixed costs by the contribution margin per unit:
- Break-Even Units = Fixed Costs / (Selling Price per Unit − Variable Cost per Unit)
- Formula (revenue): Fixed Costs / Contribution Margin Ratio
- Contribution Margin: The amount remaining from the selling price after subtracting the variable cost per unit. The amount contributed to covering fixed costs and generating profit.
- Margin of Safety: The amount by which actual sales exceed the break-even level of sales. The amount that sales can decline before the company incurs losses.
- Degree of Operating Leverage (DOL): A measure of how sensitive profits are to changes in sales volume. A high DOL means high fixed costs and high volatility.
Importance
CVP analysis helps managers make decisions about pricing, production levels, and cost control. It provides a clear understanding of the financial impact of operational changes.
Example: A company sells a product for $100 per unit. Variable costs are $60 per unit, and fixed costs are $200,000. The contribution margin is $40 per unit. The break-even point is 5,000 units ($200,000 / $40). To achieve a target profit of $100,000, the company needs to sell 7,500 units ($300,000 / $40).
10. Fintech and the Future of Finance
10.1 Fintech
Fintech (financial technology) refers to the use of technology to improve and automate financial services. It is disrupting traditional financial institutions by offering faster, cheaper, and more accessible services.
Key Fintech Sectors:
- Payments: Digital wallets (PayPal, Venmo, Alipay), peer-to-peer transfers, mobile payments.
- Lending: Online lending platforms, peer-to-peer lending (LendingClub, Prosper), crowdfunding (Kickstarter, Indiegogo).
- Investment: Robo-advisors (Betterment, Wealthfront), commission-free trading (Robinhood), social trading.
- Insurance (Insurtech): Online insurance, usage-based insurance, peer-to-peer insurance.
- Blockchain and Cryptocurrency: Bitcoin, Ethereum, decentralized finance (DeFi), smart contracts.
- Regtech: Technology to help comply with regulations — KYC (Know Your Customer), AML (Anti-Money Laundering).
- Personal Finance: Budgeting apps, financial planning tools (Mint, YNAB).
Impact of Fintech:
- Accessibility: Financial services for the unbanked and underbanked.
- Speed: Faster transactions and processing.
- Cost Reduction: Lower fees and operating costs.
- Innovation: New business models and products.
- Disruption: Traditional institutions must adapt or face decline.
Importance
Fintech is transforming the financial landscape. It is making financial services more inclusive, efficient, and customer-centric.
Example: A small business owner in a developing country uses a mobile payment app to receive payments from customers, without needing a traditional bank account. The app provides affordable, accessible financial services that were previously unavailable.
10.2 Blockchain and Cryptocurrency
Blockchain is a decentralized, distributed ledger that records transactions across many computers. It is the technology underlying cryptocurrencies like Bitcoin and Ethereum.
Key Features:
- Decentralization: No central authority — the network is maintained by participants.
- Transparency: Transactions are visible to all participants.
- Immutability: Once recorded, transactions cannot be altered.
- Security: Cryptographic techniques ensure security.
- Smart Contracts: Self-executing contracts with the terms directly written into code.
Cryptocurrency:
- Bitcoin: The first and most well-known cryptocurrency. A store of value and medium of exchange.
- Ethereum: Supports smart contracts and decentralized applications (DApps).
- Stablecoins: Cryptocurrencies pegged to a stable asset (USDT, USDC).
Decentralized Finance (DeFi):
Financial services built on blockchain, without intermediaries — lending, borrowing, trading, earning interest.
Importance
Blockchain and cryptocurrency have the potential to revolutionize finance by removing intermediaries, increasing transparency, and enabling new business models.
Example: A user sends $1,000 worth of Bitcoin to a friend overseas. The transaction is completed in minutes, with low fees, without needing a bank or intermediary. The transaction is recorded on the blockchain, visible to all, and cannot be reversed or altered.
10.3 Artificial Intelligence in Finance
Artificial Intelligence (AI) is the use of computer systems to perform tasks that typically require human intelligence — learning, reasoning, decision-making. AI is rapidly transforming finance.
AI Applications in Finance:
- Algorithmic Trading: Using computers to execute trades based on pre-defined rules.
- High-Frequency Trading (HFT): Trades executed in microseconds.
- Risk Management: AI models assess credit risk, market risk, and fraud risk.
- Fraud Detection: AI identifies suspicious transactions and patterns.
- Personalized Finance: AI provides personalized financial advice, investment recommendations, and robo-advisory services.
- Chatbots: AI-powered customer service.
- Sentiment Analysis: AI analyzes news, social media, and market sentiment to predict price movements.
- Portfolio Optimization: AI helps construct optimal portfolios.
Importance
AI is making finance faster, more accurate, and more efficient. It enables data-driven decision-making and creates new opportunities.
Example: A bank uses AI to analyze customer data and predict which customers are at risk of defaulting on loans. The bank can proactively offer assistance or restructure the loan, reducing losses and improving customer satisfaction.
11. Conclusion: The Enduring Importance of Finance
Finance is not just a subject — it is a life skill and a professional foundation. It helps individuals live financially stable lives, helps businesses grow intelligently, and helps economies function smoothly.
For students in BBA, MBA, CFA, ACCA, and ICMA programs, finance serves as a core field linking accounting, economics, management, and strategy. Understanding finance deeply means understanding how the world really works with money.
From the time value of money to capital budgeting, from risk management to behavioral finance, from financial markets to fintech — the principles of finance guide the allocation of resources, the creation of wealth, and the achievement of financial goals.
In an increasingly complex and interconnected world, financial literacy is more important than ever. Whether you are managing your personal finances, leading a corporation, or shaping public policy, finance provides the tools and frameworks for making sound decisions.
So, embrace finance. Learn its principles, apply its tools, and make informed decisions. Your future — and the future of the economy — depends on it.